Kifiya is an AI ecosystem technology infrastructure company specializing in alternative data-driven decision making, intelligent financial, digital agriculture, and infrastructure. Since 2012 we have been innovating in building robust technological infrastructures and implementing transformative initiatives that address market failures. Kifiya enables micro, small, and medium enterprises (MSMEs), smallholder farmers, and low- to middle-income consumers access to appropriate and relevant financial services.
Kifiya Financial Technology is driving a major transformation in Ethiopia’s MSME lending ecosystem. Through its flagship Sustainable Access to Finance to Enable Entrepreneurship (SAFEE) program, it aims to unlock up to USD 300 million in uncollateralized loans for MSMEs from six partner banks. It aims to transform access to finance for women- and youth-led enterprises, driving financial inclusion and creating job opportunities for young people. This initiative is supported by a USD 75 million transitional liquidity and guarantee facility, along with a USD 25 million technical assistance facility. This will enable more than 477,861 MSMEs to access uncollateralized digital credit products, while providing 425,000 young women with access to mobile device financing. Over five years, the program is expected to create up to 2.18 million work opportunities for youth and support other initiatives to generate an additional 3.79 million job opportunities.
Kifiya extends financial services to the unbanked by embedding a hands-on, agent-driven support model. Recognising that financial inclusion requires not just products but proactive support, Kifiya has placed agents at the core of its onboarding approach.

“
The loans have helped me grow my business, expand my products, and improve my income. With careful planning, they can truly transform your business.
PROFILE Name: Tigist Shumye Asega
Region: Alem Bank, Addis Ababa
Age: 36 years
Business size: Nano-enterprise
No. of employees:
Years in business: 1 year
Loan disbursed: 107,147 ETB
Loan platform: Michu (COOP Bank)
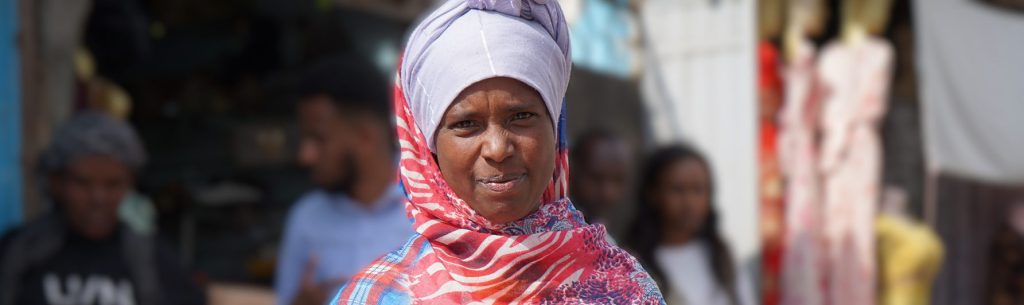
Tigist Shumeye, a 36-year-old entrepreneur living in Alem Bank, Addis Ababa, launched her nano-enterprise selling plastics, soaps, and basic cleaning items on the street to support her family. Like many informal business owners in Ethiopia, she lacked access to formal credit and faced financial instability in her early days.
That changed in November 2024 when Helen Melaku, a Customer Acquisition and Relationship Executive, referred to as Business Development Executives (BDE) agent from Kifiya, approached her on the street and introduced her to the Michu digital loan platform. With no prior experience in formal lending, Tigist was hesitant, but Helen walked her through the entire process, from understanding eligibility to navigating the mobile platform.
Thanks to this hands-on support, Tigist received her first loan of ETB 3,605 within just three days. That capital helped her restock inventory and expand her offerings beyond scouring pads to include buckets and soaps. With Helen’s continued encouragement, Tigist successfully repaid her loan in 14 days, paving the way for two additional loans, with amounts increasing progressively, enabling her to scale up steadily. Helen remained closely involved throughout, providing reminders, savings advice, and guidance on aligning borrowing with cash flow. Over time, Tigist came to view Helen not just as an advisor but as a sister-like figure that helped transformed her business.
Before accessing credit, Tigist’s business had limited scope and income. Selling a small selection of cleaning products on the street, she possessed little capital to invest and lacked a reliable way to grow. Without financial support, her ability to meet customer demand or expand her offerings remained unattainable. That changed with her first Michu digital loan.
With ETB 3,605 loan in hand, Tigist restocked inventory and introduced new products like plastic buckets and soap. The additional capital helped her draw in more customers, and as she repaid her loans on time, she became eligible for larger amounts, eventually increasing to ETB 5,000 across 22 loan cycles, totalling ETB 107,147. This steady infusion of credit translated into real business gains. Her weekly revenue has grown to approximately ETB 500, giving her greater financial control and the ability to manage day-to-day operations more confidently. The increased capital, greater revenue, and diversified products have built her business resilience and help sustain operations during slow sales periods. More importantly, the loans have shifted Tigist’s mindset from survival to growth. She is now planning to formalize her business, secure a permanent storefront, and expand into personal care and cleaning supplies. What started as a necessity-driven venture has evolved into a viable enterprise.
The hands-on support from Helen, Tigist’s BDE agent, went beyond facilitating access to digital finance. From the beginning, Helen not only guided her through the loan application process and the Michu mobile platform but also helped her build essential financial management skills. These skills enabled Tigist to manage her loans more responsibly. With each successive loan, her confidence and comfort in handling her business finances continued to grow.
Beyond onboarding, Helen played a key role in developing Tigist’s financial management skills. She provided regular advice on saving, tracking expenses, and aligning loan repayments with her business cash flow. These lessons enabled Tigist to plan more effectively, manage her inventory more efficiently, and maintain sufficient liquidity to keep her business running, even during slow sales periods. With continued encouragement from Helen, Tigist also began applying digital skills in her day-to-day operations. From using mobile banking for transactions to monitoring her cash flow, these practical capabilities have strengthened her business and improved her decision-making. She now feels better equipped to handle unexpected expenses and is more strategic in managing stock and pricing. Importantly, the trust and mentorship provided by her BDE agent have had a lasting impact. Helen’s consistent follow-up and encouragement helped Tigist shift to running her enterprise with a long-term mindset. Now more confident in her abilities, Tigist shares these skills with other women entrepreneurs, amplifying the impact of BDE support far beyond her own business.
Tigist’s growing business and improved skills have brought stability to her household. With consistent income from her expanded product offerings, she can now cover her child’s school fees and contribute to the household rent, relieving pressure on daily expenses and providing a stronger foundation for her family’s future. Tigist has built a more secure and hopeful livelihood.
In addition to the impact Tigist has on her family, her success hasn’t gone unnoticed in her community. As she expanded her inventory to include in-demand items, customers began to rely on her as a trusted local vendor. The positive feedback she received inspired her to consider formalizing her business and securing a permanent shop, both to better serve her customers and avoid losing them due to frequent relocations caused by street vending regulations. Beyond her shop, Tigist has become a source of encouragement to others. She actively shares her experience with fellow women entrepreneurs, several of whom have since applied for loans through Michu. She demonstrated that, with the right support and planning, women like her can lead change in their communities.
Tigist envisions transforming her street-side business into a permanent, licensed storefront with a wider range of products. With her growing confidence and improved financial discipline, she is steadily working toward formalizing her enterprise.
To realize this vision, Tigist plans to expand into new product categories, including personal care and cleaning supplies, based on the evolving needs of her community. She also hopes to hire sales assistants to help manage daily operations, giving her more time to focus on growth. Throughout her journey, Helen, Tigist’s BDE agent, has played a central role in providing guidance on business planning and growth. As Tigist pursues her next milestones, the mentorship and encouragement she received will continue to guide her path forward.
Kifiya’s partnership with the Mastercard Foundation, the Sustainable Access to Finance to Enable Entrepreneurship (SAFEE)
program, aims to enable MSME growth and resilience by expanding financial inclusion and access to productive credit at scale.
To support these strategic shifts in the market, the SAFEE program targets four key objectives:
• Facilitate and enable MSME access to affordable uncollateralized finance through credit scoring and digital lending
• Enable the design of innovative and relevant financial products and services tailored to the specific needs of MSMEs
• Enable financial institutions (particularly Banks) to embrace non-collateral lending and allocate capital for MSME growth.
• Foster a robust enabling environment for technology adoption and digital solutions in the financial sector.

Email: info@kifiya.com
Phone: +251 116 671 579